
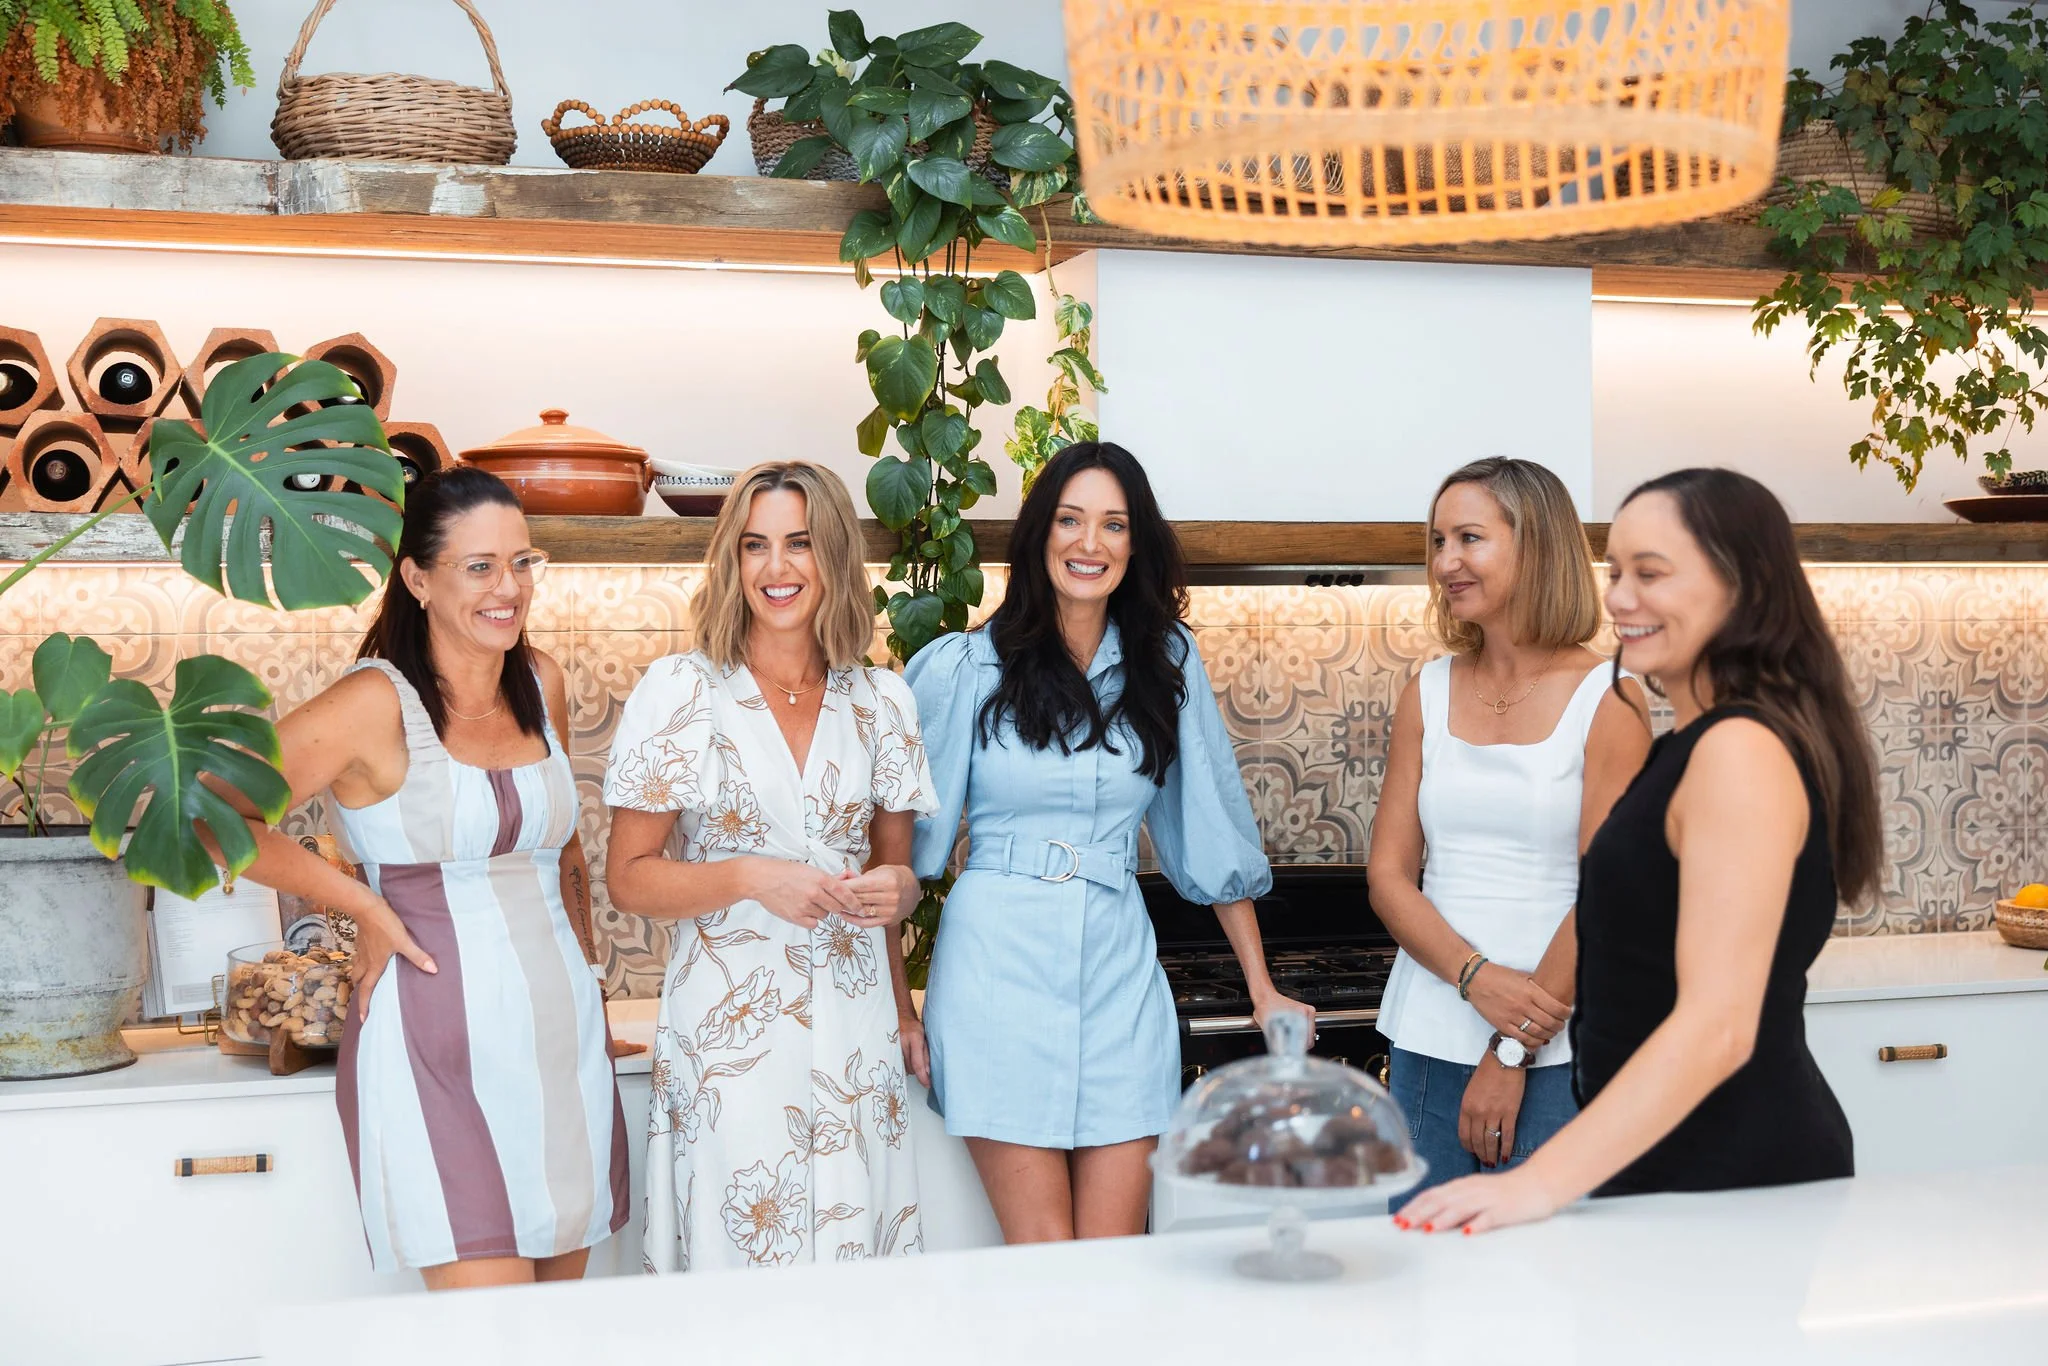
Noosaville runs on business owners. Your home loan should understand that.
Kate Sadler and The Broker Society help self employed Noosaville buyers, owners and investors get assessed properly, working from our office right here on Gympie Terrace.
A town built by the people who own it
Walk down Gympie Terrace on any given morning and most of the businesses you pass are locally owned, the cafes, the boat hire operators, the trades, the consultants working out of a spare room with a river view. Noosaville has one of the highest concentrations of self employed residents anywhere on the Sunshine Coast, and yet self employed applicants are still the group most likely to get a lukewarm response from a bank. That is exactly the gap we work in. We are based right here in Noosaville, at Shop 9, 201 Gympie Terrace, and self employed lending is one of the things Kate has built almost two decades of experience around.
Lenders on our panel
Combined years working with self employed clients
Brokers, every one of them self employed
Your Noosaville broker
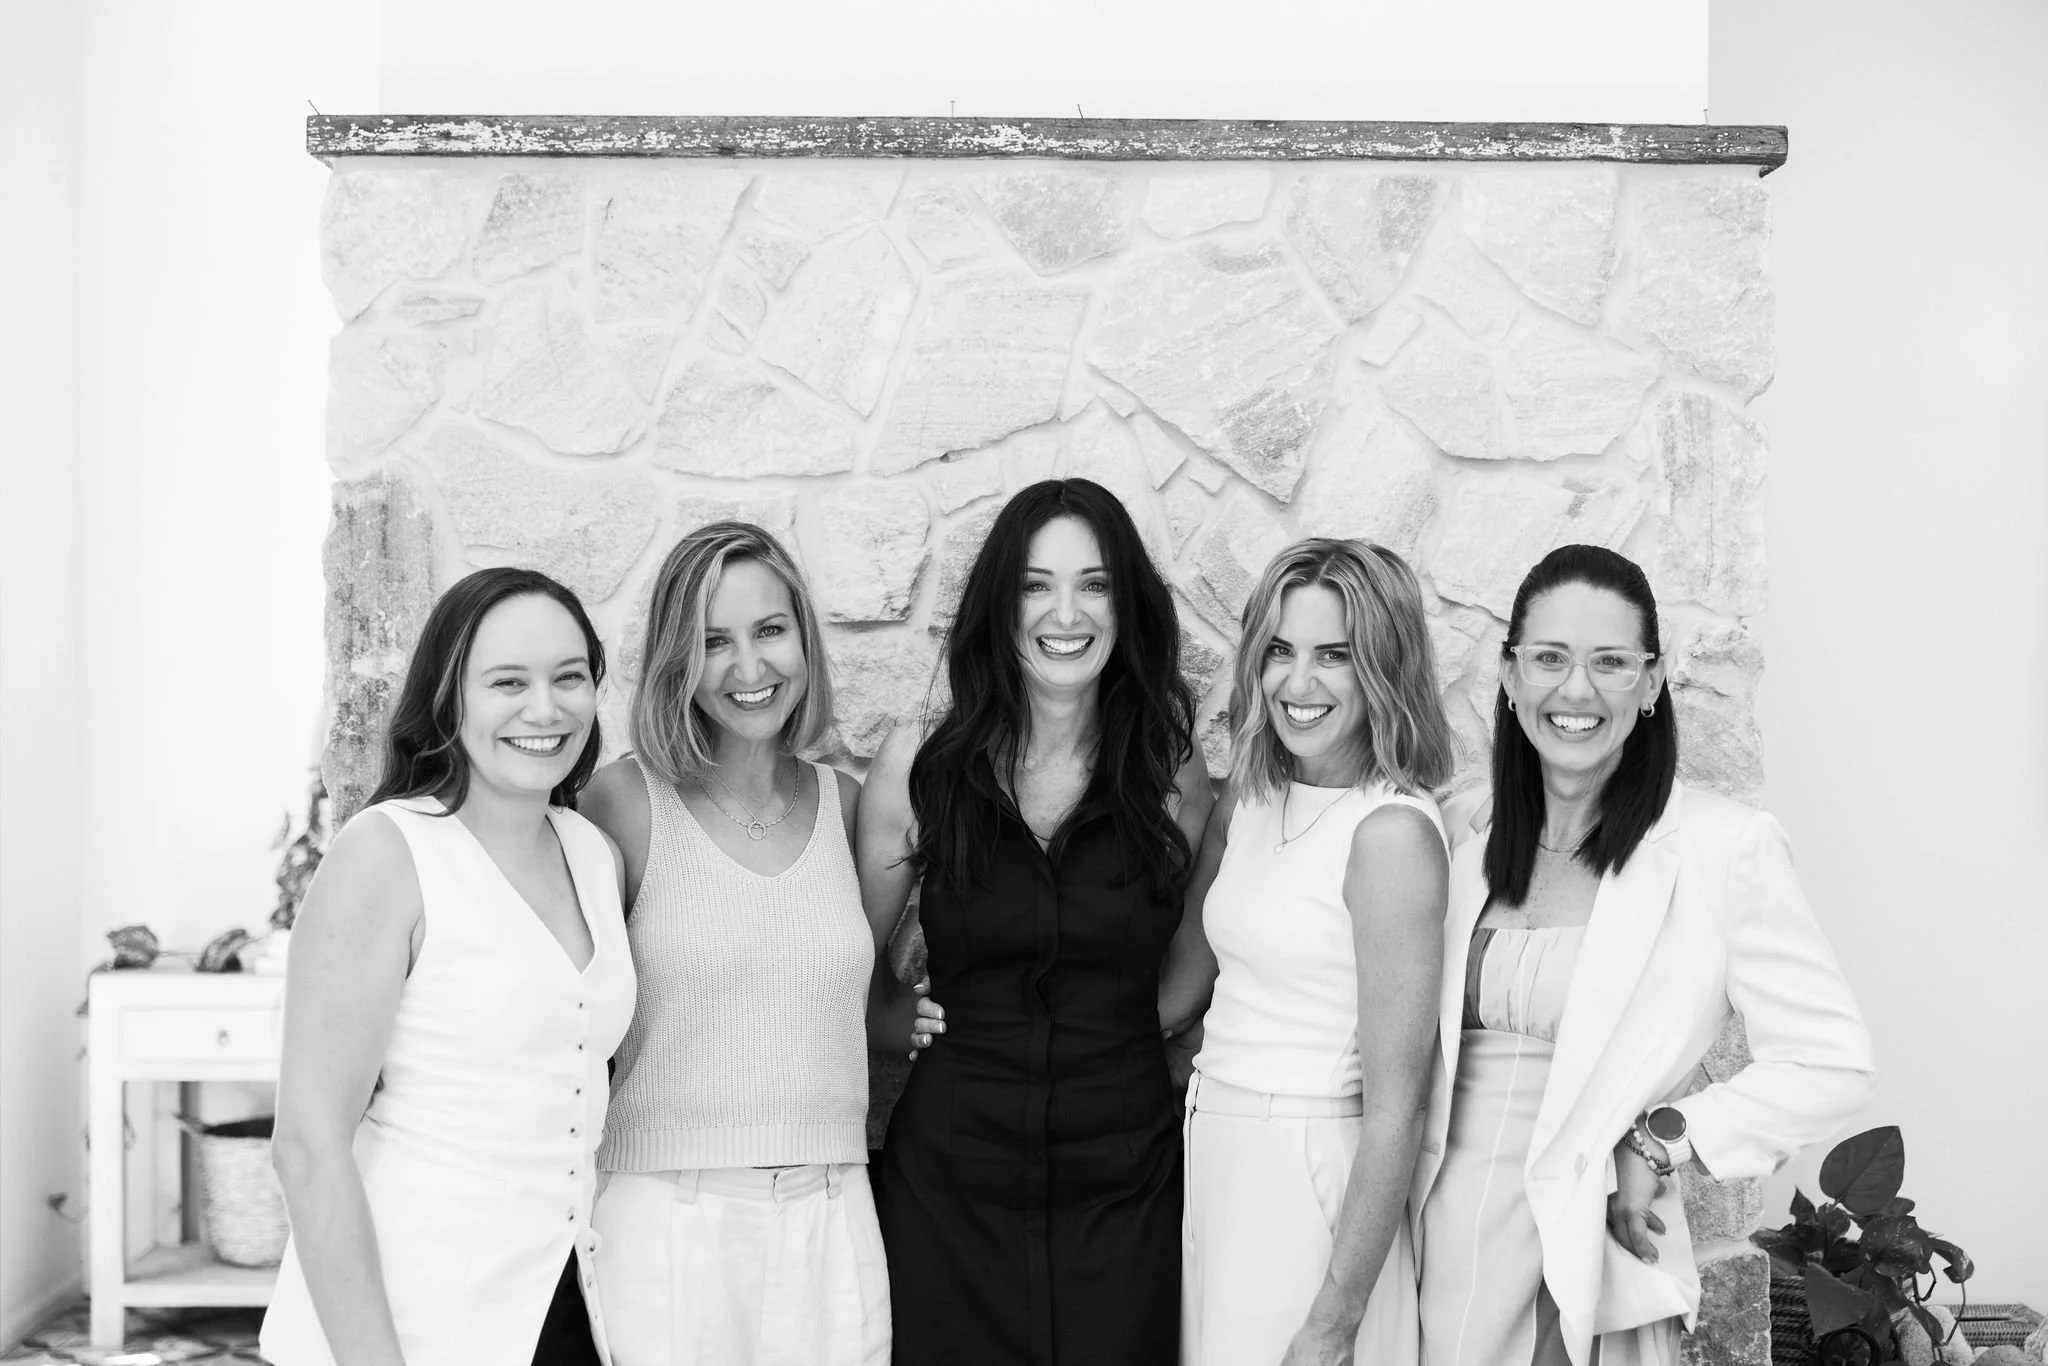
Kate Sadler founded The Broker Society in 2021 after nearly two decades in banking and broking, and self employed and complex lending has always been the work she gravitates towards, the deals a bank might shy away from. Based right here in Noosaville, Kate has built her reputation on genuinely understanding business income rather than forcing it into a standard checklist.
Kate works alongside the rest of The Broker Society's team of five brokers and dedicated support staff, covering the Sunshine Coast, Gold Coast, Brisbane's Southside and Central Queensland. Whatever a Noosaville client needs, whether it is a specialist self employed structure, an SMSF purchase, or simply a second opinion, there is always someone across the business with the right experience to bring in.
Run your own business? Let's get your lending sorted properly.
Whether you are buying your first place, refinancing, or growing a portfolio, Kate and the wider Broker Society team understand how self employed income actually works.
Beyond the home loan
Self employed Noosaville clients rarely come to us with just one question. Once your home loan is sorted, it is common to look at investment loans to start building a portfolio, SMSF lending if you are ready to purchase through your super, or commercial lending if your business is outgrowing a rented space. If you already own and it has been a while since your loan was reviewed, refinancing is worth a look too, particularly once your business income has strengthened since your last application. And if the deposit is the sticking point, our first home buyers page and our 5% and 2% deposit scheme page cover what is genuinely available, including for self employed applicants.
What to expect working with us
A proper first conversation
No forms up front. We talk through your business and your goals before anything else happens.
Face to face or online, your choice
Meet in our Noosaville office or jump on a video call. Either way, we share our screen and walk you through the visuals and numbers on your loan and lender options together.
Paperwork handled properly
We manage the application and liaise with the lender, presenting your business income the right way from the start.
Support after settlement
The relationship does not end at settlement. We stay available as your business and your goals evolve.
Explore more of what we do, or find your area.
Self employed home loan questions, answered straight
No. Kate and the wider Broker Society team work with self employed clients across Noosaville, the Sunshine Coast and Australia wide, by phone, video or in person.
Generally lenders look for at least one to two years, though this varies by lender and structure. We will assess your specific situation before assuming a standard rule applies.
Full doc uses two years of tax returns and financials. Low doc suits businesses with strong trading history but tax returns that understate income. Alt doc uses Business Activity Statements as evidence of turnover. We assess which fits your paperwork.
Potentially, depending on the lender and your industry. Some lenders will consider one year of financials alongside other supporting evidence. We can tell you honestly where you stand.
It changes how your income is assessed rather than making it harder outright. Directors and trustees are assessed on the appropriate basis for their structure, and we handle this regularly.
Yes, in the right circumstances. Low doc lending is not limited to investors or existing owners, though eligibility depends on your specific business and income situation.
Some do, since they only look at what is declared as taxable income. We work with lenders who take a broader, more sensible view of business income and cash flow.
Yes, being self employed does not rule you out. It does take a bit more preparation on the income side, which we can help you get right before you apply.
Often, yes, and it is a common reason self employed clients come back to us. Stronger, more established income can open up better options than when you first applied.
Yes. We structure investment lending for self employed clients with an eye on long-term borrowing capacity, not just the next approval.
Yes, subject to eligibility. This is a common path for established Noosaville business owners, and we work alongside your accountant and financial adviser on the specialist requirements.
It can, but seasonal or fluctuating income is common across Noosaville's tourism and hospitality sectors, and we work with lenders experienced in assessing it fairly.
A panel of 50 or more, which matters here given how differently lenders assess self employed and business income.
Get in touch directly to discuss your situation and we will explain how the process works from there.
Recent tax returns or financials, your ABN details and an overview of your business, but honestly, come as you are for the first chat and we will tell you exactly what is needed after that.
Book a time through the appointments page and Kate will take it from there.
Address:
Shop 9/201 Gympie Terrace Noosaville
Hours:
Monday–Friday
9am - 5pm
Alternate bookings by request
Email:
hello@thebrokersociety.com.au