
Acreage, lifestyle and hinterland finance, structured properly.
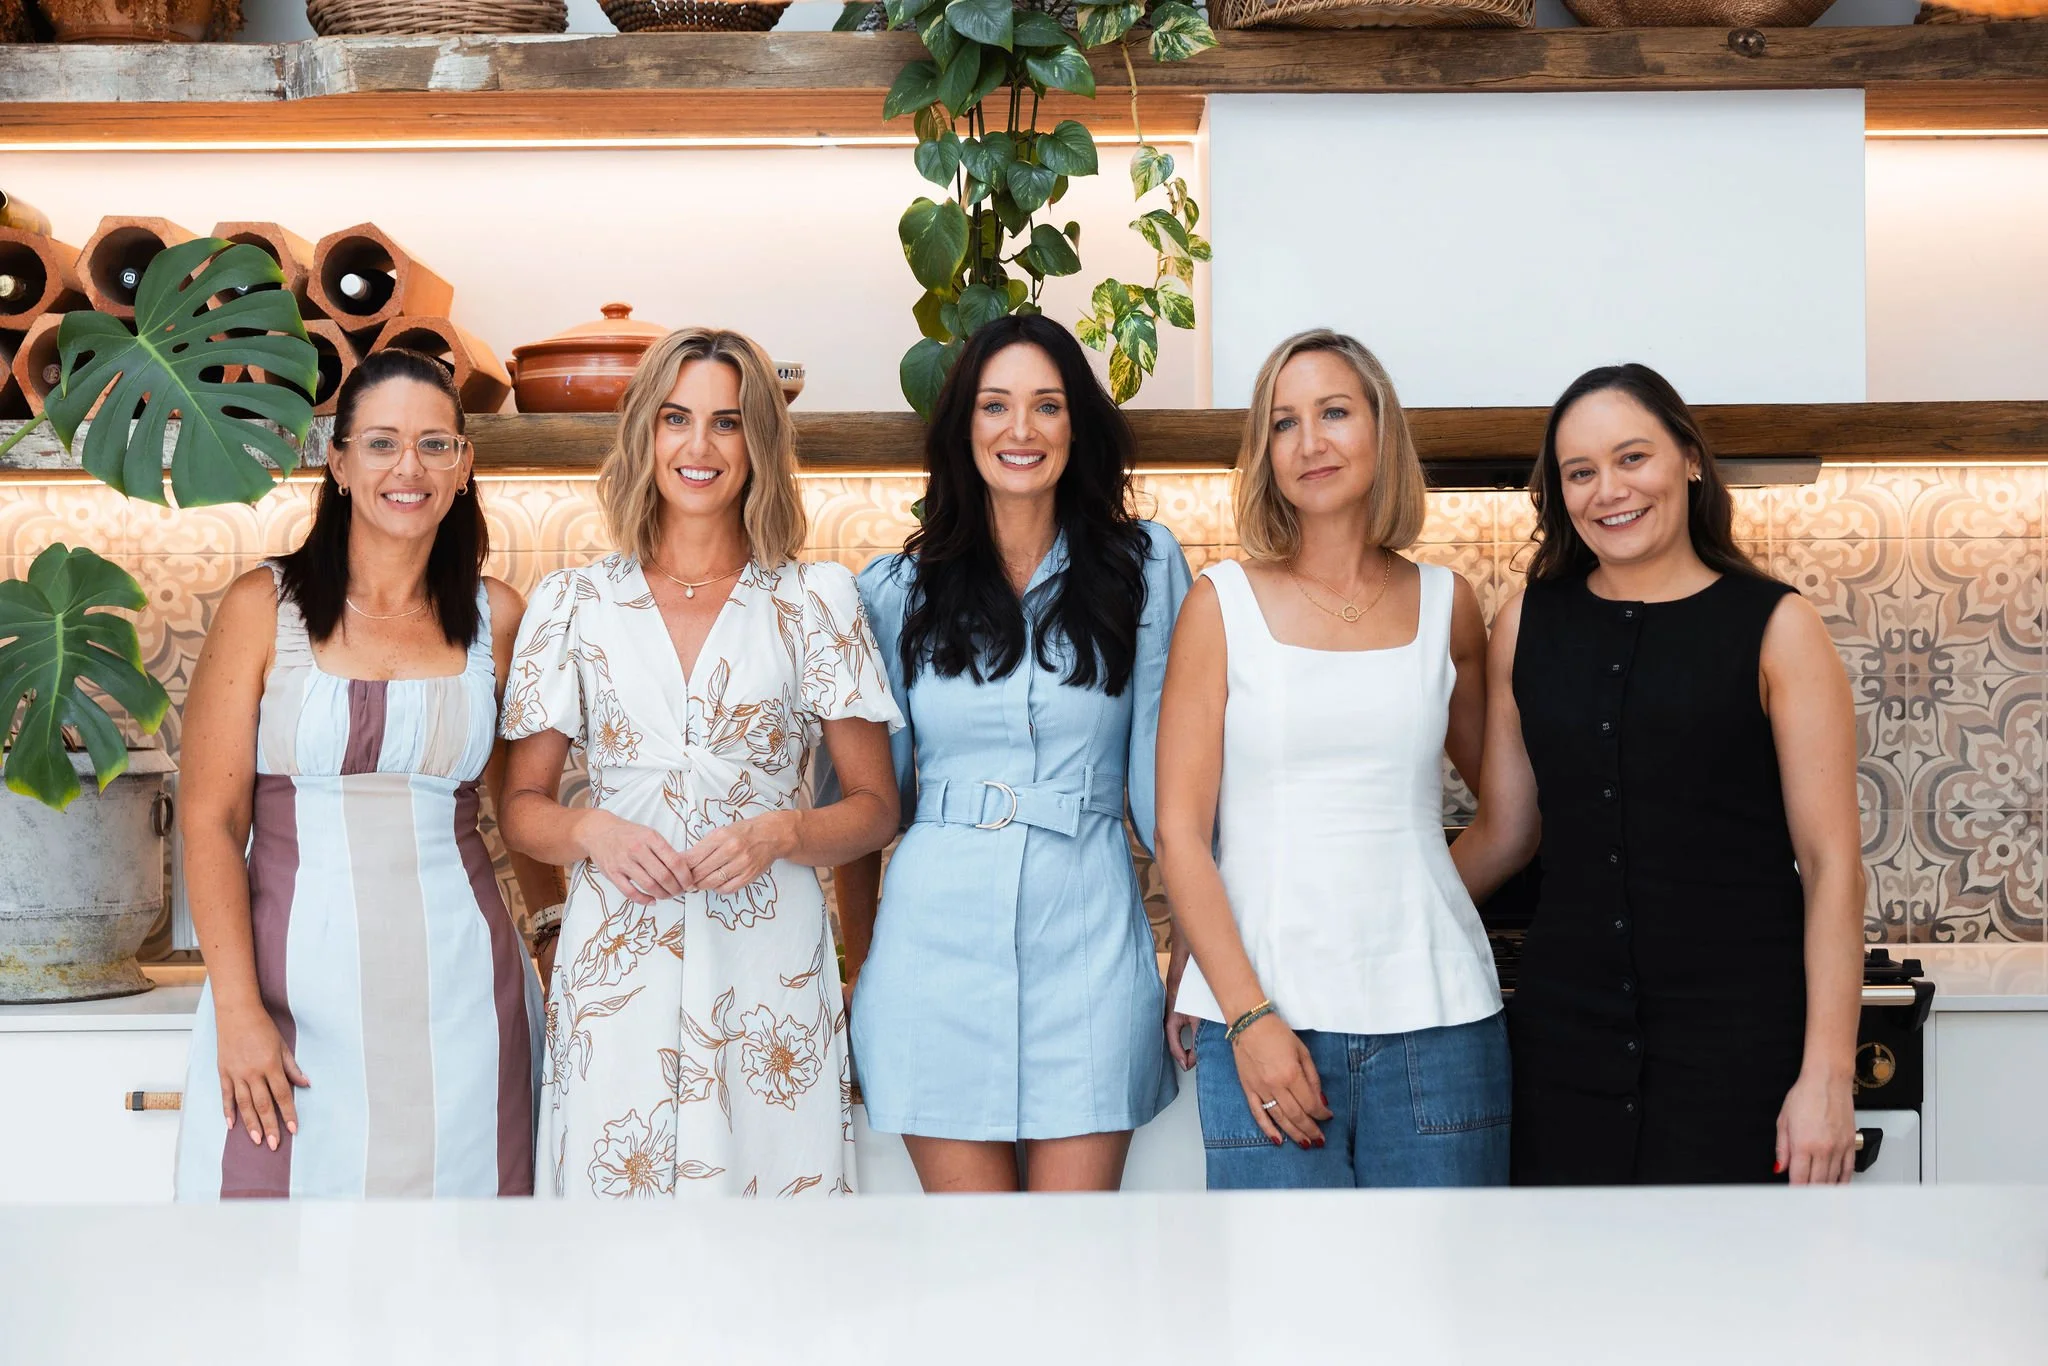
Kate Sadler works with buyers, owners and investors across Doonan and the wider Noosa Hinterland, backed by the full Broker Society team, with straightforward advice and no bank bias.
Finance for a market that moves fast and rewards being ready
Doonan is not a suburb where properties sit around waiting for the right buyer to wander past. Acreage blocks with hinterland and coastal views, architecturally designed homes and tightly held estates tend to move between buyers who already have their finance sorted. Kate sees the same pattern again and again: the clients who move quickly are the ones who had a proper conversation about lending before they started looking, not after they found the place. Some are lifestyle buyers relocating from interstate. Others are self-employed professionals whose income does not sit neatly on a payslip. A growing number are already local, sitting on years of hinterland growth and wondering what it actually means for their next move.
Kate works through the detail properly, including the parts of acreage and rural residential lending that catch people out, before recommending anything.
A hinterland community that still feels like one
Drive Valley Drive or Panorama Drive on a quiet morning and it is easy to see why people give up city life for this. But behind the views, Doonan is full of people making genuinely complicated decisions. Families relocating from interstate who need finance sorted before they have even found the block. Long-term locals who bought before the hinterland boom, now weighing up whether to extend, rebuild, or sell into a market they barely recognise. Business owners running consultancies or trades from a home office, who need a broker who understands what their income actually looks like. Kate has sat across the table from all of these people, more than once, and knows that a Doonan lending conversation rarely fits a template.
Your Doonan broker
Kate Sadler founded The Broker Society in 2021 after almost two decades in banking and broking, tired of watching bank-side advice serve the institution more than the client. She started in banking at seventeen and bought her own first home at eighteen, so the pressure of a premium market is not theoretical to her. Kate has also rebuilt her own property position after a period of overextension earlier in her career, which shapes how she talks Doonan clients through serviceability, equity and long-term strategy rather than just the next approval. She leads the Doonan and wider Noosa Hinterland work personally, with the rest of The Broker Society's five-broker team behind her whenever a client's situation calls for extra hands or a specific regional lens.
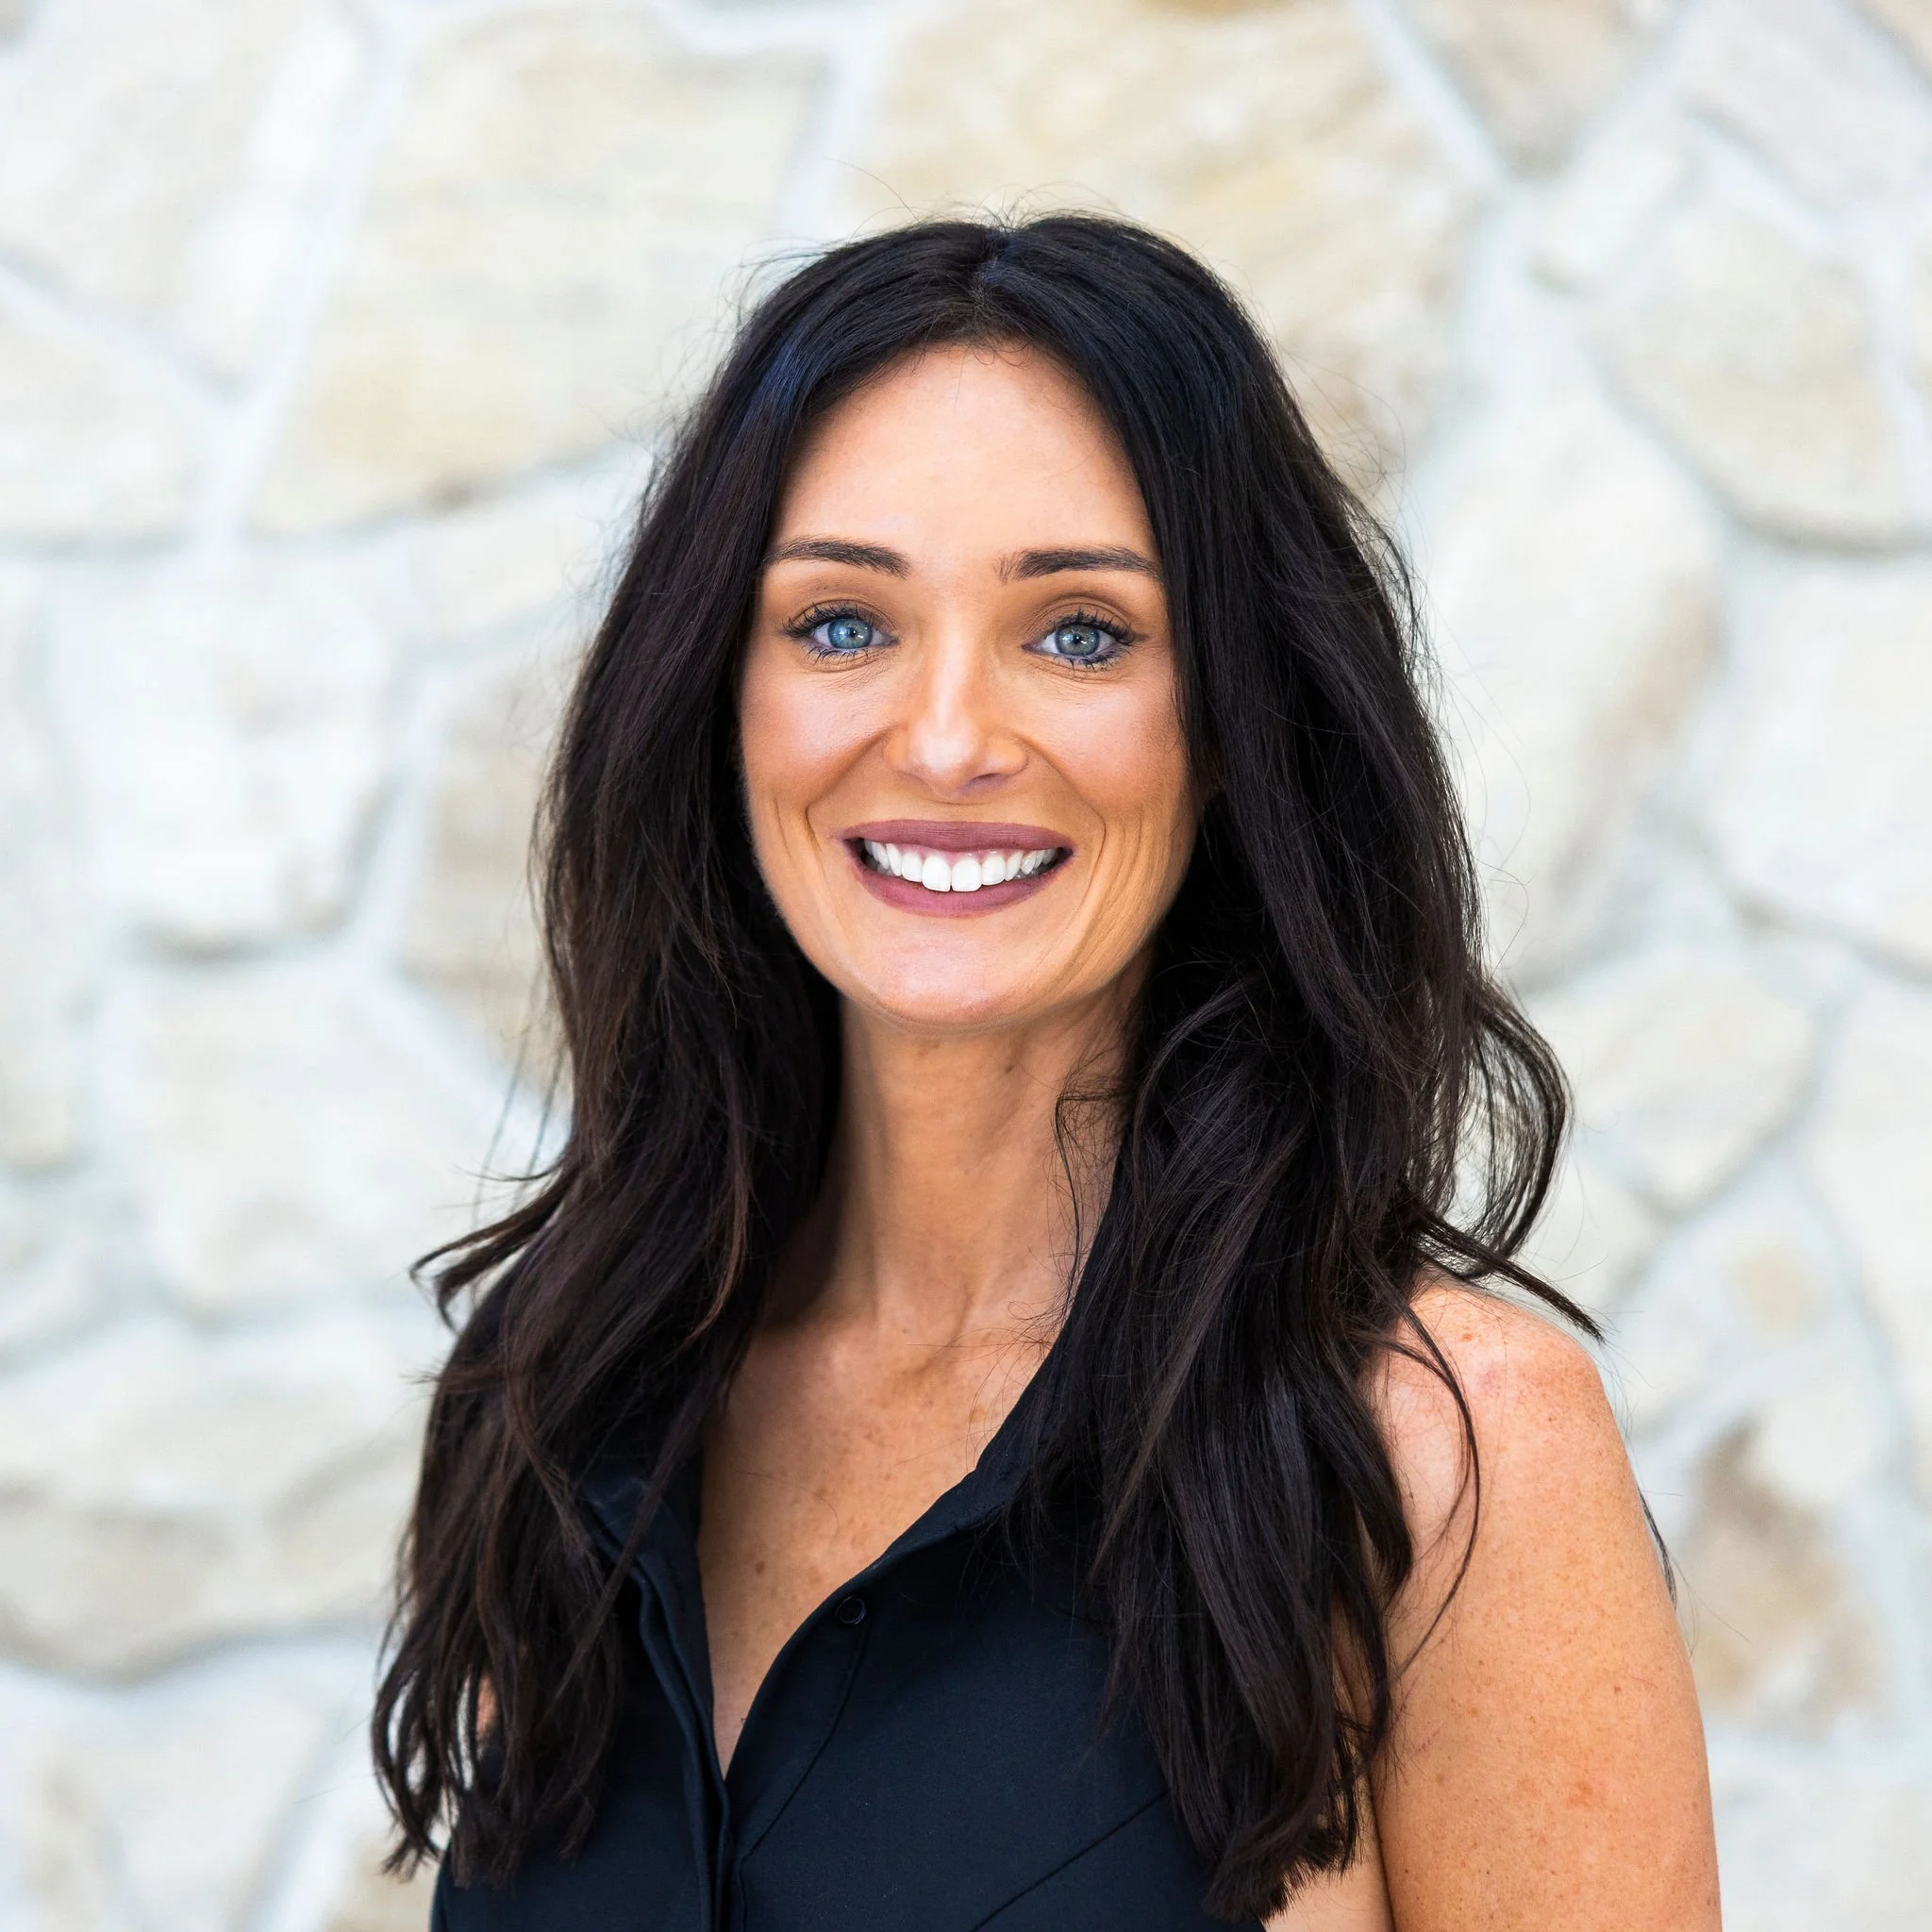
What to expect working with Kate
A proper first conversation
No forms up front. Kate talks through your situation and goals before anything else happens.
A clear lender comparison
Options drawn from a panel of 50+ lenders, including those suited to acreage and rural residential.
Paperwork handled properly
Kate manages the application and liaises with the lender so you are not chasing anyone.
Support after settlement
The relationship does not end at settlement. Kate stays available as your situation changes.
Doonan lending questions, answered straight
Do I need to live in Doonan to work with Kate?
No. Kate and the wider Broker Society team work with clients across Doonan, the Noosa Hinterland and Australia wide, by phone, video or in person.
Does buying an acreage property change how lenders assess me?
Yes, in ways that catch people out. Land size, zoning and property type all affect which lenders will consider a Doonan acreage purchase. Kate will steer you to the ones that fit.
Can first home buyers realistically buy in Doonan?
It is a premium market, so it takes the right strategy. Kate will walk you through what deposit schemes and lending pathways are genuinely available for your circumstances.
I am self-employed. Will that make finance harder here?
Not with the right lender. Doonan has a high concentration of business owners and self-employed professionals, and Kate knows which lenders assess that income fairly.
What if my income does not fit a standard lending checklist?
Low doc lending is built for exactly that. Kate will assess whether it suits your situation or whether a mainstream lender can still work with better structuring.
Is it worth refinancing if I bought in Doonan years ago?
Often, yes. Hinterland growth has shifted a lot of owners into a stronger equity position than they realise, and Kate can tell you honestly if a change is worthwhile.
Is Doonan a good spot for an investment property?
The tightly held stock and strong rental demand make it worth considering. Kate structures investment lending with long-term borrowing capacity in mind, not just the next approval.
Can you arrange finance for a commercial property or business premises?
Yes, for local business owners looking to buy premises, expand or refinance existing commercial debt.
Can I use my superannuation to buy property here?
SMSF lending is available for eligible clients. Kate will explain how it works and whether it fits your retirement strategy.
We are planning to build on an acreage block. What finance applies?
Construction lending, structured around progress payments and your builder's requirements. Kate will map the drawdown schedule out before you sign anything.
I want to sell and buy in Doonan. Can finance bridge the gap?
Yes. Bridging finance lets you secure a purchase before your existing property sells, so you are not forced into a rushed sale.
I have debts spread across cards and personal loans. Can they be combined?
Often, yes. The Reset looks at consolidating scattered debt into a single, clearer repayment structure where it makes sense.
How many lenders can Kate compare for a Doonan purchase?
A panel of 50 or more, which matters here given how differently lenders treat acreage and rural residential properties.
How Kate and The Broker Society help Doonan buyers and owners
Kate leads the Doonan and wider Noosa work personally, and draws on the full Broker Society team behind her when a client's situation calls for it. First home buyers taking on Doonan's premium price points get a clear-eyed look at first home buyer lending and what is genuinely achievable. Clients ready to move further into the hinterland or trade up to a bigger block work through buying your next home, timed properly against a sale. Owners who bought years ago and are sitting on strong hinterland growth often start with refinancing, while those building a rental portfolio in a tightly held market lean on investment loans, structured for the long game rather than a quick approval.
Doonan has a high concentration of business owners and self-employed professionals, and Kate, together with the rest of The Broker Society, works through self employed home loans and low doc home loans for income that does not fit a standard checklist. Clients purchasing through their super are supported through SMSF lending, and those with premises or equipment needs work through commercial lending. Households consolidating scattered repayments are guided through The Reset debt consolidation, and anyone building their dream home on an acreage block is supported through construction loans, coordinated with your builder from the start. When timing between selling and buying gets tight, bridging finance keeps the move on track. Wherever your situation needs a second set of eyes, Kate brings in the right broker from the wider team.
Ready to talk Doonan finance?
Whether you are buying your first hinterland home, building on acreage, or reviewing what you already own, Kate and the wider Broker Society team are a phone call away.